Buying a home can feel like a cakewalk until the financing begins. How much can you borrow? Which documents will the lender ask for? What happens after you submit the application? And how long does it take to actually receive the loan?
Understanding the home loan process beforehand can make these stages easier to navigate. From checking eligibility and comparing loan terms to verification, sanction and disbursement, every stage affects how smoothly the application moves forward.
For Pune homebuyers considering established locations such as Amanora Park Town, knowing the likely loan amount and EMI can also help set a practical property budget. This guide breaks down the home loan process step by step, so buyers know what to prepare and what to expect at each stage.
What Does the Home Loan Process Involve?
The home loan process in India involves assessing the borrower’s financial profile, verifying the property and deciding the loan amount the lender is willing to provide.
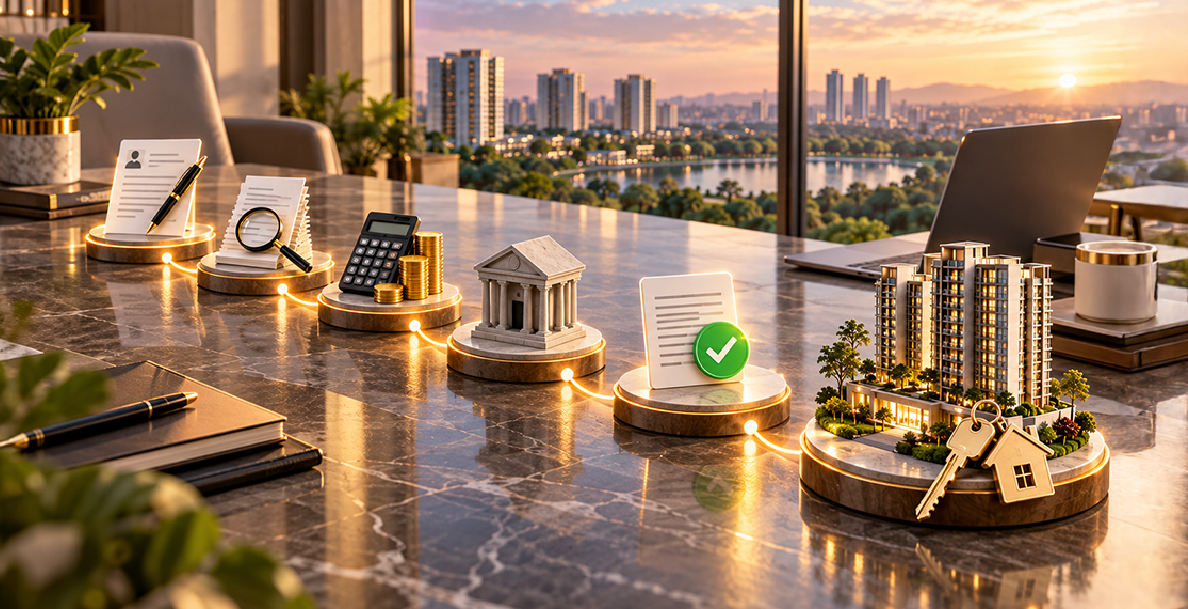
The broad journey includes application, documentation, credit assessment, property verification, sanction and disbursement. HDFC Bank’s published process includes legal and technical checks before the loan is disbursed.
The process can also begin before a property is finalized, allowing buyers to understand their potential eligibility and budget in advance.
What Are the Steps in the Home Loan Process?
Step 1: Check Your Home Loan Eligibility
The first step is to determine how much you may be able to borrow. Lenders generally consider income, age, existing EMIs, credit history, repayment capacity and employment or business stability.
A home loan eligibility calculator can provide an initial estimate using details such as income, existing obligations, tenure and interest rate. The final eligibility is determined after the lender reviews the application and supporting documents.
Step 2: Calculate Your Loan Amount and EMI
Once you have an estimated eligibility amount, compare it with the property’s price and the amount you can contribute yourself.
It is also important to compare home loan interest rates before choosing a loan. The rate can affect both the EMI and the total interest payable over the loan tenure.
For floating-rate loans, borrowers should also understand how changes in the applicable benchmark may affect the EMI or tenure.
Step 3: Submit the Home Loan Application
After deciding on the approximate loan amount, the borrower can begin the home loan application process.
The application generally requires personal, employment, income and property details. A co-applicant may also need to provide their information and documents.
HDFC Bank’s online flow includes checking eligibility, entering applicant and property details, selecting a loan offer, uploading documents and paying the applicable processing fee.
Step 4: Submit the Required Documents
Keeping the required home loan documents ready can help the application move more efficiently.
| Category | Typical documents |
| Identity | PAN, Aadhaar, passport or other accepted KYC documents |
| Address | Valid address proof |
| Salaried income | Salary slips, bank statements and Form 16/IT returns |
| Self-employed income | ITRs, financial statements and business account statements |
| Property | Agreement, allotment letter, title documents and other property papers |
The exact requirements can vary according to the applicant and property. Additional documents may also be requested during assessment or sanction.
Step 5: Credit Assessment and Verification
Once the documents are submitted, the lender evaluates the borrower’s financial profile.
The home loan verification process can involve checking income, liabilities, credit history, repayment capacity and employment or business details. Field-level verification may also be conducted in some cases.
The outcome helps the lender determine the loan amount for which the applicant may qualify.
Step 6: Property Legal and Technical Verification
Getting the borrower approved does not automatically mean the property is ready for financing.
The lender may examine title documents, the sale agreement, applicable approvals and other property records. A technical assessment may also review construction, sanctioned plans and the property’s value.
For resale properties, the lender may require the complete chain of title documents. This makes property verification an important part of the bank home loan process.
Step 7: Home Loan Sanction
Once the relevant assessments are completed, the approved loan amount is communicated through a sanction letter.
The home loan sanction process generally outlines the sanctioned amount, interest rate, interest type, tenure, EMI and conditions that need to be fulfilled before disbursement.
A sanction does not mean that the funds have already been released. Certain property and documentation requirements may still need to be completed.
Step 8: Sign the Loan Agreement
Before disbursement, the borrower completes the required formalities and signs the loan agreement.
This is the point to review the sanctioned amount, interest rate, tenure, EMI, charges and other applicable terms carefully.
Step 9: Home Loan Disbursement
The final stage is the home loan disbursement process.
After the required checks are completed, the borrower’s contribution has been paid, and the necessary property documents are submitted, the lender can initiate disbursement.
For a completed resale property, funds may be released according to the sale transaction. For an under-construction property, disbursement can take place in instalments linked to construction progress and the developer’s payment schedule.
What Happens After the Home Loan Is Disbursed?
Once the loan is disbursed, repayment begins according to the agreed schedule. Home loan EMIs generally include both principal and interest.
For an under-construction property, a pre-EMI phase may apply depending on the disbursement structure and loan terms.
Borrowers should continue tracking the outstanding principal, interest rate, EMI and remaining tenure throughout the loan period.
How Does the Process Work for First-Time Homebuyers?
For a first-time homebuyer home loan, understanding the sequence can make the borrowing decision easier. First-time buyers should check eligibility before selecting a property, estimate an affordable EMI, keep KYC and income documents ready, verify the property’s legal status and compare applicable loan terms.
Someone considering property in Hadapsar, for example, should look at the property price, own contribution and expected EMI together rather than relying only on the advertised price. This approach can also help when comparing larger developments such as Amanora Park Town, where property prices may vary according to configuration, floor and other factors.
How Long Does Home Loan Approval Take?
The home loan approval time can vary between applications. It depends on factors such as document completeness, the applicant’s financial profile and the time required for property-related legal and technical checks.
Incomplete documents or discrepancies in income, credit or property records can result in additional checks and extend the timeline. Rather than relying on a fixed number of days, applicants should focus on providing accurate information and all documents requested by the lender.
What Mistakes Should Homebuyers Avoid?
A few common mistakes can make the process more complicated:
- Choosing a loan amount without checking affordability
- Ignoring existing EMIs while calculating eligibility
- Submitting incomplete documents
- Comparing loans only on the headline interest rate
- Assuming sanction means immediate disbursement
- Overlooking property documents before purchase
- Signing the loan agreement without reviewing its terms
Final Thoughts
A home loan becomes easier to manage when buyers know what happens at each stage. Start by checking eligibility and affordability, prepare the required documents, complete credit and property verification, review the sanction terms and then proceed towards disbursement.
Whether it is a first home or a property purchase in Pune, understanding the complete process can help buyers plan their finances with greater clarity.
FAQs
1. What are the steps in the home loan process?
The home loan process generally includes checking eligibility, calculating the loan amount and EMI, submitting the application and documents, credit and property verification, loan sanction, signing the agreement and final disbursement.
2. What documents are required for a home loan?
Common home loan documents required include KYC and address proof, income documents, bank statements and property-related papers. The exact requirements can vary depending on the borrower’s profile and the property.
3. How long does it take to get a home loan approved?
The home loan approval time depends on factors such as the applicant’s financial profile, document completeness, credit assessment and property verification. Delays can occur if additional documents or checks are required.
4. What is checked during the home loan verification process?
The home loan verification process can involve checking the borrower’s income, existing liabilities, credit history, repayment capacity and employment or business details. The lender may also verify the property before approving the loan.
5. What is the difference between home loan sanction and disbursement?
Loan sanction confirms the amount and terms approved by the lender. Disbursement is the actual release of the loan amount after the required documentation, property checks and other conditions have been completed.
6. Can first-time buyers apply for a home loan?
Yes. A first-time home buyer home loan can be considered based on factors such as income, age, credit profile, repayment capacity and the lender’s applicable eligibility requirements. Checking eligibility before finalizing a property can help buyers plan their budget.